5 Basic Principles of Finance Every Business Owner Must Know
I once watched a shop owner celebrate a record sales month while quietly borrowing from his brother to pay the electricity bill. His shelves were full, his till was ringing, and his bank account was empty. Nothing was stolen. Nothing was mismanaged in the way most people imagine. He simply did not know the five principles below, and the business punished him for it.
Finance, for a business owner, is not a degree subject. It is five working principles. Get them right and the business can survive your mistakes. Get them wrong and it will eventually collapse under its own weight, no matter how good the product is.
Key Takeaways
- Profit on paper means nothing if the cash is not in the account when the bills fall due.
- An owner who cannot name their margins is running the business on hope, not arithmetic.
- Mixing personal and business money is the fastest way to misread how the business is really doing.
- Every expense is a bet: spending that grows the business is investment; spending that only looks busy is waste.
- Reserves are what turn a bad month into a story you tell later, instead of the ending.
1. Cash flow is not profit — and timing decides who survives
This is the principle that kills the most businesses, and the one most owners resist the longest. Profit is an accounting opinion. Cash flow is a fact. You can be profitable on paper and still fail to make payroll, because the two are measured in different units: profit is measured in sales minus costs, while cash flow is measured in money actually received minus money actually paid.
Here is the honest version of the equation, from a long-running guide on financial fundamentals for business owners:
Beginning Cash Balance + Cash Inflows − Cash Outflows = Ending Cash Balance
That is it. Everything else is commentary. Loan money that arrives in your account is a cash inflow, but it is not income. Repaying that loan is a cash outflow, but it is not an expense. Owner withdrawals drain cash without touching the profit figure. This is why, as that same guide points out, you can show a profit and still have a negative cash flow — or have plenty of cash coming in from borrowing and still be losing money on the actual business. (Entrepreneur, Financial Fundamentals)
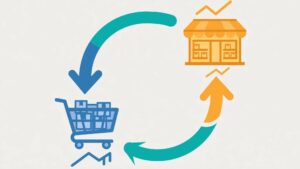
The timing layer is where businesses actually die. A lesson I picked up from studying other owners’ mistakes: customers often pay in 60 to 90 days while suppliers want their money in 15. You deliver the work, the invoice sits unpaid for two months, and meanwhile the rent, the wages and the supplier invoices all fall due on time. Finance people call this the cash conversion cycle — the time between paying out cash and getting it back — and a long one strangles even profitable businesses. (FasterCapital on margins and cash flow)
Practical response: invoice early, chase late payments without embarrassment, negotiate longer terms with suppliers than you give customers, and never confuse a big invoice with money in the bank. For a closer look at how profitable-looking businesses run out of money, see the cash flow trap that leaves six-figure earners broke, and the sequence most owners get wrong: cash flow before assets.
2. Profit has layers — know what each one tells you
When someone says “we made a profit,” the correct reply is: which one? Profit arrives in layers, and each layer answers a different question.
Revenues − Cost of Goods Sold = Gross Profit − Overhead Expenses = Net Profit
Revenue is the top line: everything the business sold. Gross profit subtracts only the direct costs of what you sold — materials, direct labour. It tells you whether the core thing you sell is viable at all. Net profit subtracts everything else: rent, wages, marketing, taxes, interest. It tells you what the business actually keeps. (The profit equations are laid out step by step in this plain-English guide to small business finances.)
The logic behind the layers: most owners fixate on revenue because it is big and flattering. But revenue tells you nothing about efficiency. A business with high revenue and a thin gross margin is working harder, not better — every sale carries almost no cushion, so one cost increase or one bad month wipes it out. Gross margin tells you whether your pricing and your production costs make sense. Net margin tells you whether the whole operation, overhead included, is worth running.
Here is the honest version of margin arithmetic. Net profit margin = (Net profit ÷ Revenue) × 100. If your business sells 100,000 worth of goods in a year and keeps 8,000 after every cost, your net margin is 8%. That 8% is the only part of the 100,000 that is truly yours. The rest was passing through your hands on its way to someone else. Read that twice before boasting about turnover.
An honesty check most owners skip: if your net margin is under 5% year after year, you do not have a pricing problem or a sales problem — you have a model problem. Either costs are too high, prices are too low, or the business is too small to absorb its overhead. Raising sales on a 3% margin just builds a bigger fragile business.
3. The business’s money is not your money
The most common fraud in small business is committed by the owner, against their own business, without realising it. It works like this: the business account has money in it, so the owner spends it — on groceries, on a holiday, on the car. Months later the accountant asks where the profit went, and the answer is: it was eaten, one personal expense at a time.
The principle is blunt. The business is a separate financial person. It has its own account, its own records, and its own profit. You, the owner, get paid in one of two honest ways: a salary you set and stick to, or a defined share of the profit, taken on a schedule — not whenever the account looks healthy. Everything else you take is an interest-free loan from your own company, and you are the least reliable borrower it has. (Deliberate Directions on separating business and personal finances)
There is a second reason beyond discipline. When the money is mixed, you cannot read the business. Is it profitable? You have no idea, because half the expenses are personal and half the income went to the kitchen. Owners in this position make every decision by gut — when to raise prices, when to hire, when to cut — because the numbers were never allowed to exist. How successful businessmen think about money differently starts with exactly this separation: they treat the business as an entity they serve, not a wallet they raid.
4. Every pound you spend is a bet on the future
Every expense is really a question: will this money come back worth more than it cost? That is the entire discipline of business spending, and it divides expenses into two kinds.
Spending to grow is investment, not expense. Stock for a proven product, a skilled hire who multiplies output, marketing with a measured return — this is money planted. I learned this the hard way in my own early ventures: the periods where I spent nothing were not the periods I saved money, they were the periods nothing grew. You cannot earn without first spending; the trick is spending on things that return.
Spending to look busy is waste. The fancy office before the revenue exists. The premium tools the free version already does. The conference trip that was really a holiday. These expenses feel like progress because they are visible, but they return nothing, and they are funded by the same cash pool that was supposed to keep the business alive in month three.
Two ideas keep this discipline honest. The first is opportunity cost: every unit of money spent here cannot be spent there, so the real cost of the fancy office is the marketing campaign you did not run. The second is the sunk cost rule: money already spent is gone and should not decide future spending. The shop that keeps a dead product line alive “because we already invested in it” is throwing good money after bad. (Drake Insurance on budgeting and cash flow forecasting)
Budgeting is how this principle gets enforced weekly: a plan for where the money goes before it goes, and a forecast of what comes in so the plan survives contact with reality. If you are starting with nothing, the zero-capital strategy for starting with nothing is the purest form of this discipline — every expense has to justify itself, because there is no cushion.
5. A business without reserves is a gamble, not a plan
Every business has bad months. A key client pays late. A supplier raises prices. A season dips. The principle is simple: the business needs a buffer between a bad month and death, and that buffer is cash you refuse to spend when times are good.
Think of it as the business’s emergency fund. Three to six months of core operating costs sitting untouched is the commonly cited target, and the logic is straightforward: it buys you time. Time to fix the problem instead of panicking. Time to negotiate instead of begging. The businesses that die in downturns are rarely the worst businesses — they are the ones with no margin for error. Cash flow before assets is the order that keeps them alive: liquidity first, empire second.
Reserves also fund the only honest form of growth: reinvestment. Profit that stays in the business — better equipment, deeper stock, stronger marketing — compounds. Profit that is all withdrawn keeps the business exactly the same size forever, while its costs quietly grow around it. The reinvestment engine behind compounding shows how this works mechanically, and how to build a profitable business that creates generational wealth puts it in the long frame: businesses that keep and reinvest their earnings become assets; businesses that are drained stay jobs.
Who these principles will not save
Honesty requires this section. These principles organise a business that has a real product, real customers, and real demand. They will not save a business nobody wants — no amount of cash-flow discipline fixes a product people do not buy. They will not save an owner who knows the numbers and ignores them anyway. And they are not a substitute for legal and tax advice: when the sums get serious, a qualified accountant earns their fee many times over.
If the business is already in trouble, the principles still apply but the order changes: stop the bleeding first, understand the numbers second, rebuild third. The comeback framework for recovering from business losses walks through that sequence properly.
How many months can your business survive?
This quick tool applies principle one to your own numbers. Enter what you have and what moves each month, and it tells you how long the business lasts if income stopped tomorrow. Example figures below are illustrations only — use your real numbers.
The formula, so you can check the tool’s working: runway (in months) = cash on hand ÷ (monthly outflows − monthly inflows). If outflows are at or below inflows, the business is cash-positive and the runway is effectively unlimited — the buffer grows instead of shrinking. This is our own calculation, built from the cash-flow equation above.
Frequently asked questions
What is the difference between cash flow and profit?
Profit is sales minus costs on paper; cash flow is money actually received minus money actually paid. They differ because of timing — customers who pay in 90 days count as revenue today but not as cash — and because loans, repayments and owner withdrawals move cash without being income or expenses. A business can be profitable and cash-poor at the same time.
How do I calculate my net profit margin?
Divide net profit (everything left after all costs, taxes and interest) by total revenue, then multiply by 100. A net margin of 8% means you keep 8 out of every 100 of sales. Track it monthly: a falling margin is an early warning that costs are creeping up or prices are drifting down.
Should I keep my business money in a separate account?
Yes, always. A separate account stops personal spending from hiding inside the business's numbers, makes the real profit visible, and turns tax time from an archaeology project into a report. Pay yourself a fixed salary or a scheduled share of profit instead of dipping in whenever the balance looks healthy.
How much cash reserve should a small business keep?
The commonly cited target is three to six months of core operating costs. The right number depends on how lumpy your income is: steady monthly revenue needs less buffer, project-based or seasonal income needs more. Start with one month and build from there — a growing reserve is better than a perfect target you never reach.
What is the cash conversion cycle, and why does it matter?
It is the time between paying cash out (to suppliers, for stock or materials) and getting cash back in (when customers pay you). A long cycle means your money is trapped in unpaid invoices and unsold stock for months, which is how profitable businesses run out of cash. Shorten it by invoicing early, chasing late payers, and negotiating better terms with suppliers.
A quick note: this article explains general finance principles for business owners. It is educational, not financial advice — your situation may need a qualified accountant or financial professional before you act on it.
About the Author — Shurah Beel runs DataPips on his own, writing from hands-on experience in trading and entrepreneurship. His articles grow out of personal research, real lessons from building and funding small ventures, and the ongoing work of turning this publication into something useful — not from a formal financial credential.