Somewhere, right now, someone is holding $5,000 in a savings account earning almost nothing, while carrying $5,000 in credit card debt at 22%. Objectively, they should empty the savings account and wipe out the debt tonight. They won’t. And it isn’t because they haven’t done the math.
That contradiction is one of the most reliably documented findings in behavioral economics, and it isn’t a failure of arithmetic. It’s a failure of category.
The Short Answer
Mental accounting is the tendency to mentally sort money into separate categories — by source, purpose, or timing — and treat those categories as non-interchangeable, even though money is objectively fungible. It explains why a bonus gets spent on a vacation while identical salary gets saved, and why people keep low-interest savings sitting next to high-interest debt rather than using one to erase the other: emptying the “savings” bucket to pay the “debt” bucket feels like a loss, even when it’s a mathematically obvious win.
The Framework, and Who Actually Gets Credit for It
Richard Thaler introduced this in a 1985 paper and formalized it further in “Mental Accounting Matters,” and it later contributed to his Nobel Prize in economics. The core claim: standard economic theory treats money as fungible — a dollar is a dollar, its source doesn’t matter — but real people consistently violate that principle, sorting money into mental buckets by where it came from or what it’s “for,” and making decisions bucket by bucket instead of against total wealth.
The Paradox That Makes This More Than a Curiosity
The savings-and-debt example above isn’t hypothetical — it’s a documented pattern. People hold savings in a low-interest account labeled “for later” or “for emergencies” while simultaneously carrying credit card debt at a much higher rate, because the two sit in different mental accounts with different rules, and disturbing the savings bucket feels like a violation even when it’s financially the obvious move.
This is, by Thaler’s own description, one of the costliest consequences of mental accounting: people carry unnecessary financial burden specifically to preserve the psychological integrity of a mental category that has no basis in actual accounting. The debt keeps compounding. The savings keep earning almost nothing. And the person doing this usually knows the math — the bucket wins anyway.
Why a Bonus Disappears and a Raise Doesn’t
The classic finding: the exact same dollar amount, landing as salary, tends to get put aside or spent sensibly. Landing as a bonus, it goes more readily toward a vacation, new furniture, or a nice dinner out — because it’s been mentally coded as “extra” rather than income, even though your bank account doesn’t distinguish between the two deposits in any way.
Tax refunds get the same treatment, and this one deserves a direct correction: a refund isn’t a gift or a windfall at all — it’s your own money that was overwithheld throughout the year and is simply being returned. Coding it as “bonus money” rather than delayed income is a mental accounting error with a real cost, since money treated as a windfall gets spent at a noticeably higher rate than money treated as earned income.
Where the Popular Version Gets It Wrong
Here’s the part almost no personal finance article mentions: the assumption that windfalls always get spent more freely — the “house money effect” — isn’t as settled as it’s usually presented. A meta-analysis found the effect varies significantly across studies, with some research even documenting a “reverse house-money effect” — windfall income reducing spending and increasing risk aversion instead.
That matters because it means mental accounting isn’t a fixed rule that always predicts loose spending on unexpected money. The category still gets applied — windfalls still get treated differently from earned income — but which direction that treatment pushes behavior depends on context that isn’t fully mapped yet. Content that presents the house-money effect as a guaranteed, universal outcome is overstating what the research actually shows.
The Critique Worth Taking Seriously
There’s a broader, sharper version of this same caution: mental accounting is a real, Nobel-recognized framework with specific documented effects — the house money effect, income-source spending asymmetry, sunk costs tracked by account — but it gets stretched past its evidence base constantly in popular and marketing content, into a vague folk-psychology version that doesn’t engage the actual mechanisms Thaler described.
Practically, that means treating “mental accounting” as an explanation for literally any spending pattern is lazier than the concept deserves. It has specific, testable predictions — money-source asymmetry, account-based sunk costs, gain/loss framing by category — and it’s most useful when applied to one of those specific mechanisms, not waved at as a general excuse for irrational-sounding behavior.
The Trick Hidden Inside the Bias
Here’s the genuinely useful reversal: if mental accounting happens automatically and mostly against you, you can also build one deliberately, on purpose, to your own advantage.
Thaler described exactly this in his own life — setting a target donation amount to a charity at the start of each year, then mentally deducting small misfortunes (an unfair parking ticket, a minor loss) from that account instead of experiencing them as fresh losses against his regular spending. He described it as a self-built insurance policy against small annoyances — using the same category-based accounting that normally causes irrational decisions, deliberately, to make his own emotional response to bad luck smaller and more manageable.
That’s the actual takeaway most coverage misses: mental accounting isn’t purely a flaw to eliminate. It’s a tool your brain already uses constantly, and you can point it somewhere useful instead of just noticing where it’s pointed against you.
What to Actually Do With This
Force a comparison across buckets before protecting either one. Before leaving savings untouched next to a carried balance, write both numbers next to each other and ask what a stranger with no attachment to either account would do. The savings-versus-debt paradox survives specifically because the two accounts are never placed side by side in the moment of decision.
Money that compounds against you in a debt account is the same mechanism covered in how compounding debt grows while you sleep — protecting a savings bucket while that debt account compounds is choosing to lose on both sides simultaneously.
Relabel windfalls as income before deciding anything. A bonus, refund, or gift, mentally filed the moment it arrives as “just more money” rather than “extra,” gets evaluated by the same standard as a paycheck — which for most people means it survives longer before being spent.
Build a deliberate mental account instead of fighting the instinct entirely. Following Thaler’s own example, a small, explicitly-labeled “buffer” account for minor annoyances can reduce the emotional sting of small losses without requiring you to become a purely rational calculator about every dollar — which nobody actually manages to be anyway.
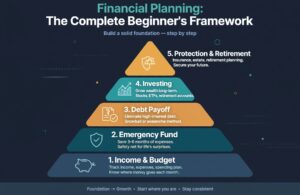
Route windfalls through the same discipline as everything else. If sequencing rules govern your ordinary income, apply the identical sequence to unexpected money rather than exempting it — buffer, debt, then discretionary — instead of letting the “extra” label skip the line entirely.
Where This Connects to the Bigger Picture
Mental accounting doesn’t operate alone. It compounds with present bias, since money labeled “extra” already feels less connected to your future self than money labeled “income” — a double reason it gets spent rather than saved. And it interacts with how badly people misjudge compounding: a windfall treated as income and invested rather than spent is exactly the kind of irregular, one-time contribution that benefits most from decades of compounding, precisely because it wasn’t already committed to a spending pattern.
Key Takeaways
- Mental accounting is the tendency to sort money into non-interchangeable mental buckets by source or purpose, even though money is objectively fungible.
- People commonly keep low-interest savings untouched while carrying high-interest debt, because spending the savings feels like violating its bucket, even though clearing the debt is the obvious financial move.
- A tax refund is delayed income, not a windfall — treating it as “bonus money” is itself the mental accounting error.
- The “house money effect” — that windfalls always get spent more freely — isn’t as settled as commonly presented; some research finds the opposite effect entirely.
- The framework has specific, testable mechanisms and gets over-applied in popular content as a vague explanation for any irrational-seeming spending.
- Mental accounting can be used deliberately, not just noticed — a self-built “buffer” account for small misfortunes is a legitimate, intentional use of the same bias.
Disclaimer: This article is for general informational purposes only and is not financial advice. Spending and saving decisions depend on individual circumstances, debt terms, and financial goals. Consult a qualified financial professional regarding your situation.
Questions Worth Asking
Why do I spend a bonus faster than the same amount from my salary?
Because the bonus gets mentally coded as “extra” money outside your normal budget, while salary is coded as income you’re used to managing carefully. The dollar amount is identical; the category assigned to it changes how freely it gets spent.
Should I use my savings to pay off high-interest debt?
In most cases, mathematically yes — the interest owed on debt typically exceeds what low-interest savings earns, so clearing the debt is usually the better move. The reluctance to do this is a textbook example of mental accounting, not a sign the reluctance is financially justified.
Does every windfall get spent more freely than earned income?
Not reliably — research on this specific effect is more mixed than commonly presented, with some studies finding windfalls actually reduce spending and increase caution instead. The category effect is real, but which direction it pushes behavior isn’t fully settled.
Is mental accounting always a bad thing to do?
Not necessarily. Used deliberately, a specific mental account for minor annoyances or a defined discretionary bucket can genuinely make financial decisions easier and reduce emotional strain, as long as it isn’t causing you to ignore an objectively better option like paying down debt with idle savings.
How should I treat a tax refund or bonus to avoid this trap?
Relabel it as income the moment it arrives, before deciding what to do with it. Running it through the same priority sequence as regular income — buffer, debt, then discretionary spending — prevents the “extra money” framing from skipping past decisions it should actually go through.