Short answer: no. At 35 you still have roughly 30 years before a typical retirement age, and 30 years of steady investing is enough to build serious wealth. What is true is that a late start has a price, and that price is measurable. This article puts the number on it, then lays out the catch-up plan that actually works, including the honest limits if what you mean by “getting into finance” is a career change rather than investing.
What “too late” really costs
The fear behind this question is usually not about age itself. It is about compounding, and compounding rewards time more than it rewards cleverness. So let us be precise instead of reassuring. The table below is our calculation: a fixed monthly investment, earning 7% a year compounded monthly, held until age 65. The 7% figure is a deliberately modest planning assumption, below the long-run nominal average of the US stock market, which has run at roughly 10% a year with dividends reinvested since 1957, or about 6.7% after inflation, according to Investopedia’s review of S&P 500 history. SoFi’s summary of the same history puts the average at about 10% a year, or 6% to 7% after inflation. Past returns do not predict future ones, which is exactly why the planning number here is lower than the historical average.
| Starting age | Years invested | Total contributed | Value at 65 (our calculation) |
|---|---|---|---|
| 25 | 40 | $144,000 | $787,000 |
| 35 | 30 | $108,000 | $366,000 |
| 45 | 20 | $72,000 | $156,000 |
Read that table twice, because it contains both the bad news and the good news. The bad news: the 25-year-old ends up with more than double the 35-year-old’s balance despite contributing only a third more money. That is the cost of ten lost years of compounding, and no clever product makes it disappear. The good news: the 35-year-old still turns $108,000 of contributions into $366,000. The 45-year-old still more than doubles their money. Starting late is expensive. Not starting at all is far more expensive, because the alternative to $366,000 is not $787,000. It is zero.
There is also a catch-up number worth knowing. To match the 25-year-old’s final balance, the 35-year-old would need to invest about $645 a month instead of $300. That is the honest trade: a late start does not close the gap with hope, it closes it with a higher savings rate. A similar comparison by Wallethacks, using $100 a month at 7%, reaches the same conclusion from the other direction: the late starter ends with far less than the early starter, but far more than the person who never starts. Which brings us to the part most articles skip.
The benchmark trap: ignore the multiples, measure your own gap
You will run into Fidelity’s well-known savings guidelines: roughly 1 times your salary saved by 30, 3 times by 40, 6 times by 50, and 10 times by 67, as set out in Fidelity’s own guidance. A second look at the same guideline, broken down by age, is available from DQYDJ’s analysis of the Fidelity multiples. These are useful as a compass and terrible as a verdict.
Here is why. The typical saver is nowhere near them. Vanguard’s data on retirement plan participants shows a median balance of under $47,000 for people aged 35 to 44, and under $79,000 for ages 45 to 54. If your income is anything above modest, those medians sit far below Fidelity’s multiples. In other words, most people your age are “behind” by this yardstick. A benchmark that nearly everyone fails is not a diagnosis, it is background noise.
What matters instead is your own gap, and it has only three inputs: what you have now, what you can invest each month, and how many years you have left. That is why calculating your net worth is the unglamorous first step. You cannot plan a catch-up until you know the starting line. If the number surprises you, good. Surprise is information, not failure.
If you mean a career in finance, not just investing
“Getting into finance” has a second meaning, and the answer changes with it. At 35, a finance career is open, but not every door is equally open, and pretending otherwise would be dishonest.
The doors that reward a 35-year-old entrant are the ones where judgment and relationships matter: financial planning and advice, corporate finance roles, risk and compliance, fintech product roles, and analysis work where a previous career becomes an advantage rather than a gap. Someone who spent a decade in operations, sales, or engineering walks into a finance role understanding how a business actually works, which a 22-year-old graduate cannot offer. Employers in advisory work in particular hire mid-career entrants regularly, because clients trust experience.
The doors that narrow are the ones built around a young-entrant pipeline: the classic investment banking analyst track, which recruits overwhelmingly from recent graduates and runs on punishing hours. It is not formally age-barred, but the structure works against a mid-career switcher, and the honest advice is to aim at adjacent roles, such as corporate development or transaction advisory, where the same skills pay without the same pipeline.
The practical route is the same in both cases: one recognised credential that fits the target role, such as the CFA for investment work or a planning qualification for advisory work, plus proof of skill through real work, not certificates alone. And the same rule applies as with investing. The question is never whether 35 is too late in the abstract. It is whether you are willing to spend the next three to five years deliberately building the new thing. Which is where an old lesson earns its place.
The five-year stretch nobody wants to hear about
A lesson I picked up along the way, from a founder who had rebuilt more than once, is that people rebrand avoidance as virtue. They call it patience, or balance, or waiting for the right time, when what they are really doing is refusing the hard stretch. His counterpoint was simple: a focused five to seven years can change a family’s entire trajectory. Not a lifetime of grind. One deliberate stretch.
That maps directly onto a 35-year-old’s finances. You do not need to be perfect for thirty years. You need to be serious for the next five: a savings rate you can defend, debts handled in the right order, and an investing habit that survives a bad year. Five years of that, and the numbers start to look different. Five years of drifting, and 40 arrives with the same question, only heavier. The stretch is the plan. Everything else is commentary.
The catch-up plan that works
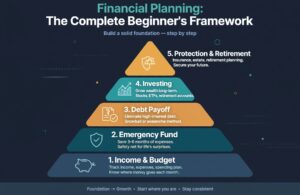
First, build the floor before the portfolio. An emergency fund comes before investing, not after, because the investor who must sell investments during a crisis is not investing at all. Our guide to why an emergency fund is your first real asset sets out the logic in full. Three to six months of essential expenses, in cash, is the floor.
Second, set the savings rate before picking investments. A 25-year-old can reach a comfortable retirement saving around 15% of income. Starting at 35, the honest figure is closer to 20%, and that is before any employer match. If 20% sounds impossible, start at 10% and raise it by one percentage point every few months, or with every pay rise. A rate that grows beats a rate that collapses.
Third, deal with expensive debt in the right order. High-interest debt compounds against you at the same speed investing compounds for you, and the maths is not close. The distinction between good debt and bad debt is the line: debt that builds earning power can wait, debt that funds consumption cannot.
Fourth, keep the investing itself boring. A broad, low-cost diversified portfolio, bought every month regardless of headlines, is the vehicle for nearly every late starter. The reason is not that it is exciting. It is that it removes the two decisions that destroy late starters: timing the market and chasing the hot thing. The rule of 72 gives you a quick sense of what your return assumption really means: at 7%, money doubles roughly every ten years, which means a 35-year-old gets about three doublings before 65. That is the engine. Your job is to keep feeding it.
Fifth, raise income where you can, because a late starter’s most powerful lever is not a better fund, it is a bigger contribution. Our breakdown of building wealth on an average salary shows the maths plainly: contributions matter more than returns when the timeline is shorter. A side income, a promotion, or a skill upgrade that lifts pay by even a modest amount can matter more than any investment choice.
What not to do: the catch-up traps
The most dangerous moment for a late starter is the moment they decide to “make up for lost time.” That phrase is how sensible people end up in leveraged trades, concentrated bets on a single stock, and schemes promising to recover a decade in a year. The logic feels urgent, but urgency is not a strategy. The market does not know you started late and owes you nothing for it.
Watch for three specific traps. First, any product that promises to compress time, such as high leverage or options strategies sold as income. Second, any adviser or influencer whose pitch starts with your regret rather than your numbers. Third, the quiet trap of lifestyle inflation at exactly the age when earnings peak: the pay rise that becomes a bigger house, a newer car, and the same savings rate as before. Compounding feels slow in the early years precisely because the growth is invisible at first, and that invisibility is what pushes people toward shortcuts. The lag phase is normal. Enduring it is the skill.
There is one more honest point. If you are starting at 35 with nothing saved and a low income, the plan above still works, but the timeline stretches: retirement may land at 67 or 70 rather than 60, and part-time work in later years may be part of the picture. That is not failure. That is a plan with its eyes open, and it beats the alternative, which is another decade of the same question.
Your first 30 days
Week one: calculate your net worth and list every debt with its interest rate. Week two: open the emergency fund account and set the first automatic transfer, even a small one. Week three: clear the highest-interest debt first or set its payoff plan, and raise your retirement contribution by whatever you can sustain. Week four: set the monthly investment on autopilot and stop checking it daily. Then repeat for five years. That is the whole programme, and its simplicity is the point.
Key Takeaways
35 is not too late, but it is not free either. Thirty years of steady investing still builds real wealth, and our calculation shows $300 a month at 7% growing to about $366,000 by 65. The price of a late start is a higher savings rate, not a riskier portfolio: matching an early starter takes roughly $645 a month, not a gamble. Benchmarks like Fidelity’s salary multiples are a compass, not a verdict, since most savers sit well below them. A finance career at 35 is realistic in advisory, corporate finance, and fintech roles, where experience counts, and narrower only in young-entrant pipelines like banking analyst tracks. The plan that works is unglamorous: emergency fund first, a rising savings rate, expensive debt cleared, boring diversified investing on autopilot, and one focused five-year stretch.
Frequently asked questions
Is 35 too late to start investing for retirement?
No. With 30 years to age 65, steady monthly investing still compounds into a substantial sum. Our calculation shows $300 a month at 7% reaching about $366,000. The cost of starting at 35 rather than 25 is real, but it is paid with a higher savings rate, not with risk.
How much should a 35-year-old invest each month?
Aim toward 20% of income including any employer match, and build up to it gradually if that is not possible today. Start with whatever you can sustain every month without fail, then raise it with each pay rise. Consistency beats a heroic rate that lasts three months.
Is 35 too old to start a career in finance?
No, but target the right roles. Financial planning, corporate finance, risk, compliance, and fintech value the judgment and work history a 35-year-old brings. The traditional investment banking analyst pipeline is the exception, since it recruits overwhelmingly from recent graduates.
Should I take bigger risks to catch up?
No. Bigger risks do not reliably compress time, and a large loss at 35 is harder to recover than a missed gain. The reliable catch-up levers are a higher savings rate, higher income, and lower fees, in that order.
What if I have debt and no savings at 35?
Work in order: a small starter emergency buffer first, then attack high-interest debt, then build the full emergency fund, then invest steadily. Trying to invest while expensive debt compounds against you is running in both directions at once.
Can I still retire at 60 if I start at 35?
It depends on your savings rate and income, and for many people the honest answer is that 65 to 67 is the realistic target. That is still a full retirement, and it is far better than the outcome of waiting until 45 to ask the same question.
A note on this article: this is general education, not personal financial advice. Returns used here are planning assumptions, not predictions, and real outcomes will differ. Before making major money decisions, consider speaking with a qualified financial professional about your own situation.
One more thought, for the reader who reached this article by searching the question at midnight. The fact that you are asking it at 35 is itself the advantage: you still have time, and you now know what the delay costs. The people in real trouble are not the ones who start at 35. They are the ones who keep asking at 45. For a closer look at the same problem from the other side, read our guide to compounding for late starters. Then start this month, not next year. The best time was 25. The second-best time is today, and unlike most advice, that sentence is actually true here, because the maths says so.
About the Author — Shurah writes and maintains DataPips independently, drawing on hands-on experience in trading and entrepreneurship. Articles are shaped by personal research, real trading lessons, and the process of building this publication from scratch, not by a formal financial credential.