Yes — by most standard measures, $100,000 saved by 35 puts you ahead of where the typical American household sits at that age, and it lines up reasonably well with common retirement savings benchmarks too. But the honest answer has a second half: the number alone doesn’t tell you whether you’re actually financially secure. That depends on what the $100,000 is made of, what debt sits against it, and which direction your savings rate is heading.
- $100,000 saved by 35 sits above the U.S. median household net worth for that age band — that’s a genuinely strong data point, not a self-help platitude.
- Net worth and retirement savings are two different measurements, and mixing them up is how most people misjudge their own progress.
- A rising savings rate matters more over the long run than a single balance captured at one point in time.
- Comparing yourself to a national benchmark is useful for calibration. Comparing yourself to a neighbor, a coworker, or a stranger online is a different exercise, and it rarely ends well.
First, “Good” Compared to What? Net Worth vs. Retirement Savings
Part of why this question is confusing is that “$100K saved” could mean two different things, and the benchmarks for each aren’t the same. Net worth is everything you own minus everything you owe — home equity, retirement accounts, cash, investments, minus your mortgage, car loan, and any other debt. Retirement savings is narrower: just what’s sitting in accounts earmarked for later, like a 401(k) or IRA.
If your $100,000 is your full net worth, here’s where that lands you. According to the Federal Reserve’s 2022 Survey of Consumer Finances, the median net worth for households under 35 was around $39,000, and for the 35–44 bracket it was closer to $135,000. So at $100,000, you’re likely well ahead of the median if you’re on the younger side of that line, and slightly behind the 35–44 median once you’re solidly into it. Either way, you’re nowhere near “behind” — you’re in a genuinely competitive range for your age group. Our guide to calculating your own net worth walks through exactly what to count if you want an accurate number instead of a guess.
How $100K Stacks Up Against Retirement Savings Benchmarks
If the $100,000 is specifically retirement money, the comparison shifts. T. Rowe Price’s widely used benchmark suggests aiming for one to one-and-a-half times your annual salary saved for retirement by 35. Under that guideline, $100,000 puts you on track if you earn somewhere between roughly $65,000 and $100,000 a year. Earn meaningfully more than that, and the same balance represents slower progress relative to your income — not a failure, just a gap worth noticing.
The point of a benchmark like this isn’t to hand you a pass-or-fail grade. It’s a mile marker, not a report card. It tells you roughly where the road is, so you can tell whether you’re behind pace, on pace, or ahead of it — and adjust accordingly.
Why the Comparison Itself Can Mislead You
Here’s where most “am I behind” questions go wrong. The Consumer Financial Protection Bureau defines financial well-being not as a specific dollar figure, but as a felt sense of control over your day-to-day finances, the capacity to absorb a shock, being on track toward your own goals, and having the freedom to make choices that let you actually enjoy your life. Two people can have identical $100,000 balances and completely different levels of actual security — one debt-free with low fixed costs, the other carrying a car loan and credit card balance that eat the cushion the moment an emergency shows up.
This is also where comparison quietly does damage instead of good. Checking a national median once, to calibrate, is healthy. Checking your progress against a specific person you know is a different habit entirely, and it rarely produces anything useful — we cover why in the comparison trap. It’s also worth remembering that visible wealth and actual net worth often point in opposite directions, which is the whole idea behind stealth wealth — the person who looks like they’re ahead of you financially is frequently the one with the smaller number sitting quietly in an account.
What Matters More Than the $100,000 Number
A few things move the needle more than the raw balance sitting in front of you right now:
- Debt load. $100,000 saved against a paid-off car and no credit card balance is a completely different position than $100,000 saved while carrying high-interest debt on the other side of the ledger.
- Your savings rate, not your savings snapshot. A 28-year-old saving 20% of their income with $40,000 banked is on a stronger trajectory than a 35-year-old with $100,000 who’s stopped contributing. The balance today is a photo. The rate is the video.
- Whether your spending grows with your income. Every raise that quietly gets absorbed into a bigger apartment or a nicer car resets your progress without you noticing — that pattern is covered in detail in why earning more never makes you richer.
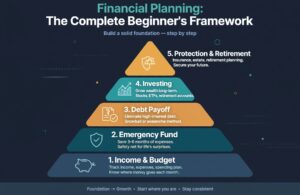
- Whether the basics are actually covered first. A real emergency fund changes what a market dip or a job loss actually costs you — see why an emergency fund is your first real asset if that piece isn’t in place yet.
If You Want the Number to Grow Faster From Here
The honest lever isn’t a clever trick — it’s what you do with money above your basic needs once it starts showing up. Our breakdown of how small, consistent investments build big wealth covers why the next ten years matter more for a $100,000 base than the first ten did. And when a bonus, raise, or windfall lands, what you do with that specific extra money — invest it, upgrade your lifestyle, or split the difference — is its own decision worth thinking through deliberately, which is exactly what we get into in status vs. skill.
The Real Answer
$100,000 saved by 35 is good by the numbers — above the national net worth median for your age group, and in line with standard retirement benchmarks for a solid range of incomes. But the more useful question isn’t whether you’ve hit a number other people set. It’s whether your debt is under control, your savings rate is still climbing, and your day-to-day finances feel like something you’re steering rather than reacting to. Get those three right, and the number takes care of itself.
Frequently Asked Questions
Is $100k a lot to have saved at 35?
Relative to the national median, yes — it’s above where most households your age currently sit. Relative to your own income, cost of living, and goals, it depends on the details covered above.
What if I have far less than $100k saved at 35?
The median itself is lower than most people assume, and the benchmarks are guideposts, not deadlines. A rising savings rate starting now will do more for your position at 45 than stressing over where you stand today.
About the Author
Shurah built DataPips from the ground up after years spent in trading and entrepreneurship. What’s published here comes from that hands-on experience and ongoing research — not a financial planning license.